'Tis The Season To Consider Seasonality!

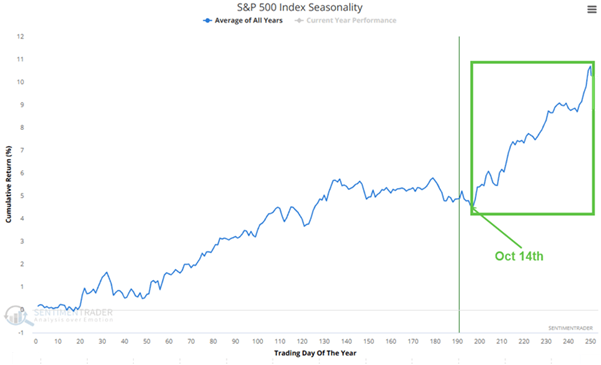
1.) SEASONALITY – Reading the investment environment based on where we are currently within the context of a long average of years is always something to keep in mind. Is it the sole reason stocks move? Of course not. But it is definitely something that big money pays attention to. So where are we now? We’re just about done with the “unfavorable” window, which ends at the close today...October 14th. The seasonal trend is then deemed 'favorable' through the end of the year. Will that drive stock returns? Not by itself…but it is not a negative either.
2.) INFLATION – For about a month now, we’ve been saying that the rate of change (RoC) for inflation has been, and is likely to continue to be – ACCELERATION. And so it is with the CPI coming in a bit hotter than “expected”. That’s funny to me…the whole “expected” thing. Why? Are we to believe that no one in markets has paid attention to how oil moved the prior month? After all, Oil is one of the biggest drivers of inflation. Anyway, what’s more important is how the market tends to look at this kind of macro scenario. And…? It’s more of a positive than not, as long as growth is accelerating with it, which it has been. Right now, stock volatility (VIX) is in a bearish trend…good for stocks…and something called “dealer gamma” is positive. Positive dealer gamma is when the big boys and girls in the options market, buy stocks when prices fall and sell them when prices rise, which helps keep the market from bouncing around too wildly. Looking ahead, we’ve got a Fed meeting on Oct 28th, the Mid-term elections on Nov 3rd and the Treasury announcement on bond issuance on Nov 4th. All of these are potential catalysts for volatility to move. But for now, we’re seeing volatility continued to be muted.
3.) MOVE – Bond volatility continues to be an important issue…and it is responding in a more healthy way, even as rates continue to rise. Even after the “hot” CPI this morning, the MOVE Index is down another -4.4% to 96 this morning. Remember, it spiked to over 114 just six days ago. Harley Bassman, the creator of the MOVE index, published a note yesterday detailing the “CTD Shift” and flip to “Negative Convexity” in long duration bonds and the implication for a surge in bond supply. Translation = there is currently a bit of a reflexive condition for bonds…where selling creates selling. This is a condition where, for longer dated bonds…think 10YR Treasury and longer…this potential selling intensifies as rates approach 6%. Recently I wrote about how bond markets react as rates move up toward big round numbers like 6% and 7%. You can read that here. Bottom line is that as the bond market continues to give positive investment signals…we’re not likely at “the bottom” just yet. It’s important to note, that when we have the macro condition of growth and inflation accelerating together, we should expect rates to move higher. How much? That’s the 64 million dollar question. Right now, rates on the US 10YR Treasury are breaking out to new highs. A close below 5.31% would be a lower high and a welcome sign for the bond market.